Politics
China to Eliminate Tariffs on Imports from African Countries

China has announced plans to eliminate tariffs on imports from all 53 African countries with which it maintains diplomatic relations.
This policy shift aims to deepen trade relations and position China as a leading trade and investment partner for the continent.
The zero-tariff initiative, when fully implemented, would expand on a 2024 agreement that removed import duties on goods from 33 African nations classified as “least developed.”
The new policy will now include larger economies like Nigeria and South Africa, further deepening trade ties between Beijing and the continent.
However, Eswatini, the only African country that maintains diplomatic relations with Taiwan, is excluded from the deal.
Middle-income African countries with more developed manufacturing and export sectors are expected to benefit significantly from this arrangement.
Nations like Kenya, South Africa, Nigeria, Egypt, and Morocco will gain duty-free access to the Chinese market, enabling them to export a wider range of processed and value-added goods without tariff barriers.
China has also pledged additional support for smaller or less industrialized African economies, promising tailored programs to help them take advantage of the new trade benefits.
Despite the optimistic tone, trade between China and Africa continues to show a significant imbalance, with China enjoying a trade surplus of around $62 billion.
Analysts warn that unless African exports to China increase substantially, this disparity may grow.
The new tariff policy is seen as a strategic move to help rebalance trade flows and strengthen Beijing’s influence on the African continent.
This initiative follows broader economic commitments made by China, including a pledge of 360 billion yuan (approximately $50 billion) in credit lines and investments over a three-year period.
The move reflects Beijing’s ongoing efforts to cement its role as a key economic partner in Africa and offer an alternative to Western-led trade systems.
With the tariff walls coming down, African nations now face the dual challenge of scaling up production capacity and ensuring the quality of exports. If successfully harnessed, the opportunity could mark a new chapter in Africa–China relations—one defined by more equitable trade and shared prosperity.





Riyadh Airport Attacks Threaten Oil, Global Trade
By Alabidun Shuaib AbdulRahman, Nigeria
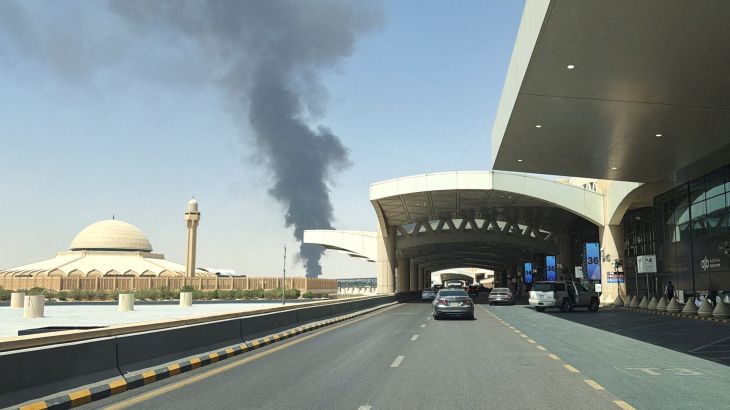
The repeated attacks on Saudi Arabia’s King Khalid International Airport in Riyadh have escalated a regional security crisis with potentially far-reaching consequences for global oil supplies, international trade, aviation, investment and economic stability. With at least 12 people killed and more than 300 injured in Saturday’s attack, followed by another reported strike on Sunday, October 11, the unfolding crisis has placed one of the world’s most strategically important energy-producing countries under renewed pressure.
The immediate concern is the safety of civilians and the protection of critical infrastructure. The broader question, however, is whether the confrontation involving Saudi Arabia and Yemen’s Houthi movement will remain contained or develop into a wider conflict capable of disrupting international commerce and energy supplies.
Saudi authorities reported that the Saturday attack killed 12 people and injured 309 others. The Saudi-led coalition subsequently reported another attack on the airport on Sunday, when an unidentified projectile reportedly struck Terminal 4 and caused a fire. Saudi air defences also intercepted a cruise missile near the airport. The facility’s operations remained suspended following the deadly Saturday attack, according to Reuters reporting on October 11.
The Houthis had warned airlines, passengers and airport workers against using Saudi airports and airspace, describing the area as a potential theatre of military operations. The movement’s warning, coupled with the renewed attacks, has raised concerns about the safety of commercial aviation and the reliability of transport connections across the Gulf.
The attacks come as Saudi Arabia seeks to strengthen its position as a global investment destination, tourism hub and international logistics centre under its Vision 2030 economic diversification programme. The kingdom has invested heavily in infrastructure, entertainment, tourism and other sectors intended to reduce its dependence on oil revenues.
Oil Markets Face Renewed Uncertainty
Saudi Arabia’s importance to the international oil market makes any escalation involving the kingdom a concern for governments, energy companies and consumers worldwide.
According to the United States Energy Information Administration, Saudi Arabia exported approximately seven million barrels of crude oil per day in 2023, accounting for 34 per cent of OPEC’s crude oil exports that year. The agency also reported that Asia received approximately 75 per cent of Saudi Arabia’s crude oil exports, with China, Japan, South Korea and India among its leading customers.
These figures illustrate why instability involving Saudi Arabia can have consequences far beyond the Middle East. Major Asian economies depend on Gulf energy supplies to support electricity generation, transportation, manufacturing and industrial production.
However, an important distinction must be made between an attack on an airport and a disruption to oil production or exports. The reported strikes on King Khalid International Airport do not, by themselves, establish that Saudi oil facilities have been damaged or that crude oil shipments have been interrupted.
The principal economic risk is that the conflict could expand to energy infrastructure, export terminals, pipelines or maritime routes used to transport petroleum.
Such an escalation could cause traders to factor a higher geopolitical risk premium into oil prices. The resulting price movements would depend on the scale of any actual supply disruption, the availability of alternative supplies and the market’s assessment of how long the conflict might last.
The stakes are particularly high because international oil markets are sensitive to disruptions at strategic transportation chokepoints.
The Strait of Hormuz, located between Iran and Oman, is one of the world’s most important oil transit routes. The EIA estimated that approximately 20.9 million barrels per day of petroleum liquids passed through the strait in the first quarter of 2025. Its September 2026 outlook subsequently reported that the volume fell to 4.9 million barrels per day in the second quarter of 2026 amid severe regional constraints.
The figures demonstrate the potential consequences of prolonged instability in the Gulf, although the latest airport attacks should not be confused with the separate developments affecting the Strait of Hormuz.
Any further escalation that threatens oil-producing facilities or maritime transport could intensify uncertainty over supply availability and prices.
For importing countries, the consequences could include higher fuel costs, increased transportation expenses and renewed inflationary pressure. Manufacturers could face more expensive energy inputs, while airlines, shipping companies and agricultural businesses could experience higher operating costs.
Oil-producing countries might benefit from increased export earnings if prices rise, but such gains would depend on their ability to maintain production and deliver crude to international markets.
Red Sea and Bab el-Mandeb: The Trade Connection
The threat to global trade extends beyond aviation because the conflict is unfolding in a region containing some of the world’s most important maritime routes.
The Bab el-Mandeb Strait connects the Gulf of Aden to the Red Sea, providing a gateway towards the Suez Canal and Mediterranean Sea. It is an important passage for commercial shipping between Asia and Europe.
The EIA estimated that approximately 4.2 million barrels per day of crude oil and petroleum products passed through Bab el-Mandeb in the first half of 2025. This represented a substantial decline from 2023 levels amid disruptions to regional shipping.
The same agency estimated that approximately 4.9 million barrels per day of crude oil and petroleum products moved through the Suez Canal and the SUMED pipeline during the first half of 2025.
These figures illustrate the strategic importance of the wider Red Sea corridor to international energy transportation.
If attacks and security threats spread further across the region, shipping companies could face increased insurance premiums, delays, rerouting costs and uncertainty over the safety of vessels and crews.
Ships unable to use the Suez Canal and Red Sea corridor safely may need to travel around the Cape of Good Hope at the southern tip of Africa. Such diversions can increase voyage distances, fuel consumption and delivery times.
The additional expenses may be passed to importers, manufacturers and consumers through higher freight charges and product prices.
For businesses operating with tight delivery schedules, even a temporary disruption can affect inventory management, production planning and contractual obligations. The consequences could be particularly significant for developing economies that rely on imported fuel, machinery, food products and industrial inputs.
African countries are not insulated from such disruptions. Many depend on international shipping to obtain petroleum products, fertilisers, pharmaceuticals, electronics and manufacturing equipment. Higher freight and energy costs can place pressure on their foreign-exchange reserves, trade balances and domestic prices.
Nevertheless, the extent of the impact would vary from country to country according to import dependence, alternative supply routes, exchange-rate conditions and the ability of governments and businesses to absorb higher costs.
The Riyadh airport attacks have not, on their own, established a new disruption to maritime traffic. Their significance lies in the wider security environment in which aviation threats, military operations and risks to regional transport networks are developing simultaneously.
Saudi Arabia’s Economic Ambitions at Risk
The attacks also present a challenge to Saudi Arabia’s economic diversification programme.
Through Vision 2030, the kingdom has sought to develop industries that can generate employment, attract private investment and reduce dependence on petroleum revenues.
Tourism, entertainment, logistics, technology, manufacturing and international events are central to this ambition.
Riyadh’s growing role as a host for international conferences and business gatherings reflects the government’s effort to establish the kingdom as a destination for global commerce.
However, these industries depend on the movement of people, goods and capital. International businesses need reliable transport connections, while tourists and event organisers require confidence that destinations are accessible and reasonably secure.
Political Implications and the Risk of Wider War
The political consequences could prove as significant as the economic effects.
United States President Donald Trump said Washington was considering joining Saudi Arabia’s offensive operations against the Houthis. His comments raise the possibility of a broader American military role in a confrontation that has already placed civilian infrastructure and international transport at risk.
British Defence Secretary Wes Streeting also suggested that the United Kingdom could potentially provide further support to Saudi Arabia.
Neither possibility should be treated as confirmation of a settled decision to participate in offensive military operations. The precise nature of any additional assistance remains important, particularly given the risk of further escalation.
What It Means for Nigeria and Africa
For Nigeria, the developments present both potential economic opportunities and significant risks.
As an oil-producing country, Nigeria could benefit from higher international crude prices through increased export earnings and government revenue, provided production and exports remain stable.
However, higher oil prices do not automatically translate into improved living standards. The domestic impact depends on production volumes, foreign-exchange availability, public expenditure, petroleum product prices and the extent to which additional revenue reaches the wider economy.
If global energy prices rise sharply, Nigerian businesses could face higher transportation, logistics and production costs. These expenses may feed into food prices, manufacturing costs and the prices of goods transported across the country.
The effects could be more difficult for countries that rely heavily on imported petroleum products and have limited fiscal capacity to absorb price shocks.
African governments should therefore monitor developments in international energy markets, review emergency preparedness and strengthen their capacity to manage external economic shocks.
Analysis
Nigeria’s 2027 Elections and the Unfinished Business of Diaspora Voting, by Boniface Ihiasota

Nigeria’s 2027 Elections and the Unfinished Business of Diaspora Voting, by Boniface Ihiasota
As Nigeria approaches the 2027 general elections, millions of Nigerians living abroad face a familiar democratic dilemma: they remain emotionally, economically and socially connected to their homeland, yet their ability to influence its political leadership through the ballot remains restricted. From London to Washington, Toronto to Johannesburg, and Dubai to other global cities, Nigerians in the diaspora have compelling reasons to prepare for the elections, even as the country continues to grapple with the legal barriers to diaspora voting.
The 2027 elections, scheduled for January 16, according to the Independent National Electoral Commission, will determine the leadership responsible for steering Nigeria through critical economic, security and governance challenges. The decisions made in Abuja and state capitals will affect citizens regardless of whether they live in Nigeria or abroad. These include exchange-rate policies, taxation, education, healthcare, security, investment regulations and the protection of property rights. Nigerians abroad therefore have legitimate reasons to follow the electoral process closely and demand accountability from those seeking public office.
However, preparation must begin with an important distinction: political participation is not the same as having a legally recognised opportunity to cast a ballot from overseas. Nigeria’s electoral framework has historically not provided for out-of-country voting. Although diaspora voting has featured in national debates and legislative proposals, the legal and administrative obstacles have remained significant.
The consequences extend beyond symbolism. Nigeria’s diaspora contributes to the economy through remittances, investment, professional expertise and business networks. The World Bank’s Migration and Development Brief estimated that Nigeria received approximately $20.9bn in personal remittances in 2022. Such financial contributions demonstrate the continuing relationship between Nigerians abroad and households at home. Yet economic contribution does not automatically translate into electoral influence. The challenge is how to ensure that citizens who contribute to national development can participate meaningfully in decisions about the country’s future.
The National Assembly has previously considered constitutional changes intended to enable diaspora voting. In March 2022, however, the proposed constitutional amendment was rejected during the legislative review process. The Nigerians in Diaspora Commission has criticised the setback, arguing that Nigerians abroad should not remain excluded from the democratic process. Subsequent proposals have continued to raise questions about electronic voting, voter verification, cybersecurity, electoral transparency and the practical cost of organising overseas polls. These concerns deserve serious consideration, but they should lead to workable solutions rather than indefinite postponement.
For Nigerians abroad, preparation for 2027 must therefore go beyond waiting for permission to vote. They can monitor INEC announcements, follow legislative developments, examine candidates’ records and scrutinise policy proposals. They can participate in lawful political discussions, support credible civic education initiatives, challenge misinformation and encourage relatives at home to make informed electoral decisions. Diaspora professionals can also contribute expertise in technology, election administration, cybersecurity and public accountability without becoming instruments of partisan manipulation.
Political parties should equally recognise that Nigerians abroad are not merely sources of remittances or occasional audiences for campaign speeches. They are citizens with knowledge of different governance systems, public institutions and economic practices. Their experiences can enrich national debate, provided their contributions are grounded in Nigeria’s realities rather than assumptions that foreign models can be transferred without adaptation.
The question surrounding the 2027 elections is not simply whether Nigerians abroad care about their country. Their sustained economic and personal connections already demonstrate that commitment. The more difficult question is whether Nigeria’s democratic institutions will create a credible, transparent and legally sound framework that allows eligible citizens overseas to exercise their electoral rights.
Until such arrangements are enacted and implemented, Nigerians abroad must remain informed, organised and engaged while respecting the law governing the elections. Democracy should not be reduced to the act of casting a ballot; it also requires informed scrutiny, civic responsibility and sustained demands for accountability. But these activities cannot permanently substitute for the right to vote.
Africa’s Resources Must Build Africa, by Alabidun Shuaib AbdulRahman
Across Africa lie enormous deposits of oil, gas, uranium, gold, lithium, cobalt, copper, diamonds and other strategic minerals, yet many of the countries sitting on these resources continue to struggle with poverty, unemployment, weak industrialisation and the steady movement of their young people towards Europe, North America and other destinations in search of better opportunities.
For decades, much of Africa’s natural wealth has travelled outward as raw material, while the greater economic value created through processing, refining, manufacturing and technology has accumulated elsewhere. Africa has supplied the resources that feed global industries, but has too often remained at the lower end of the economic chain, buying back finished products at prices far removed from what it earned when those raw materials left its soil.
That contradiction is becoming increasingly difficult to ignore because of what is happening in Niger Republic. Since General Abdourahamane Tiani came to power following the July 26, 2023 coup, his government has increasingly pursued greater control over Niger’s natural resources. What initially appeared to be part of the broader political rupture between Niamey and its former colonial power, France, has gradually developed into a wider policy of resource nationalism.
On June 19, 2025, Niger’s Council of Ministers approved the nationalisation of Société des Mines de l’Aïr, SOMAÏR, the uranium company operating at Arlit in the Agadez region. SOMAÏR was established in 1968 and began uranium production in 1971. Before nationalisation, French nuclear company Orano held 63.4 per cent, while Niger’s state mining company, SOPAMIN, held 36.6 per cent.
Between 1971 and 2024, SOMAÏR produced 81,861 tonnes of uranium, of which 80,518 tonnes were commercialised. Figures presented by the Nigerien government showed that Orano had taken 86.3 per cent of the commercialised production, while SOPAMIN accounted for 9.2 per cent.
In August 2026, the government took another step. It awarded the In Azaoua large-scale uranium mining permit in Arlit to Teloua Safeguarding Uranium Mining Company, TSUMCO, the state company created to replace SOMAÏR and continue operations over the former SOMAÏR perimeter. At its August 21 meeting, the Council of Ministers also approved the reassignment of another uranium permit, Madaouela I, to the state-linked Madaouela Mining Company.
The government has adopted a similar approach in the petroleum sector. On June 12, 2026, Niger’s Petroleum Minister, Hamadou Tini, announced that the government was reviewing the hydrocarbons code and preparing a new production-sharing contract model. He said the reforms were intended to strengthen the state’s negotiating capacity and increase the economic benefits accruing to Niger. He also disclosed plans to review provisions relating to cost recovery by petroleum operators and stressed the importance of training Nigerien professionals capable of negotiating more effectively with international companies.
Niger has also established MAZOUMAWA National Gold Company as part of its attempt to strengthen national control over gold resources and the country’s gold value chain. In January 2026, its Director-General, Abdou Ousseini, said the company intended to contribute to gold exploitation while controlling the valorisation and value chains of gold in Niger. The company had two exploration permits in the Dan Issa area and had collected more than 6,000 samples for analysis.
There is, therefore, something much bigger than the Niger-France dispute at stake. It is the ownership of Africa’s economic future.
For generations, the structure has remained remarkably familiar. Africa digs, pumps, cuts and exports. Someone elsewhere processes, refines, manufactures, finances and markets. The finished product eventually returns to African consumers at a considerably higher price.
That arrangement is not entirely without benefits. Foreign companies bring capital, technology, technical expertise, international markets and, in some cases, infrastructure that many African countries would struggle to provide on their own. The problem begins when that relationship becomes permanent, when Africa remains trapped at the extraction end of the value chain while the greater economic benefits of its resources accumulate elsewhere.
The African Union has recognised this problem for years through initiatives such as the African Mining Vision and its commodities strategy. The objective is for Africa to move from being primarily a supplier of raw materials towards greater value addition, stronger local content, higher returns from commodities and meaningful participation in global value chains.
The African Development Bank estimates that Africa possesses about 30 per cent of the world’s mineral reserves and could capture more than 10 per cent of the projected $16tn revenues from key green minerals by 2030. Yet the same institution reported that Africa received about $190.7bn in financial inflows in 2022 while losing approximately $587bn through financial leakages.
The implication is clear: Africa does not necessarily need to chase away foreign investors. It needs to become a better negotiator, a more capable participant and, ultimately, a stronger owner of the industries built around its own resources.
Botswana offers an important illustration. Its diamond industry was not built by simply shutting foreign capital out. Debswana, the company at the centre of Botswana’s diamond production, is jointly owned by the Government of Botswana and De Beers, with each holding 50 per cent. The partnership has become a major contributor to Botswana’s GDP, foreign exchange earnings and government revenue and employs about 5,000 staff and 6,000 contractors.
Tanzania has pursued another route by giving the state a minimum 16 per cent non-dilutable free-carried interest in mining companies, alongside taxation, royalties and other government participation mechanisms. Its local-content framework also seeks to ensure that Tanzanian companies participate in supplying goods and services to the mining industry.
Ghana has moved in a different direction. Rather than nationalising its gold mines, it has sought to increase domestic participation through regulation. Its 2025 local-content framework required surface mining operations to be undertaken by wholly Ghanaian-owned contractors, while underground contract mining requires at least 50 per cent Ghanaian ownership.
Zimbabwe’s lithium policy provides perhaps an even clearer example of beneficiation as a development strategy. After banning exports of unprocessed lithium ore in 2022, Zimbabwe announced in June 2025 that it would prohibit the export of lithium concentrates from January 1, 2027. The objective is to encourage greater domestic processing. Zimbabwe is Africa’s leading lithium producer, while Chinese-owned companies have invested more than $1bn in the country’s lithium sector since 2021.
If lithium is increasingly important to batteries and energy storage, Zimbabwe wants more of the economic activity generated by that demand to take place within Zimbabwe rather than elsewhere. That is precisely the direction Africa needs to consider.
The International Energy Agency reported in October 2025 that Africa captures less than one per cent of the value generated from manufacturing clean-energy technologies and their components, despite supplying around 75 per cent of global manganese, 70 per cent of cobalt and nearly 20 per cent of copper. The IEA estimates that moving into beneficiation, processing and manufacturing could raise the market value of minerals produced in Africa to about $120bn by 2040.
This is why the African Union’s Africa Green Minerals Strategy, adopted in March 2025, is significant. The strategy calls for Africa to move beyond raw mineral exports towards value addition at source, regional industrialisation, local beneficiation, job creation and economic diversification. The AU’s African Forum on Mining subsequently called for stronger continental bargaining power and high-level African critical-minerals diplomacy to ensure that mineral agreements prioritise local value addition rather than simply facilitate the export of raw materials.
Niger, therefore, should not be judged simply by whether its nationalisation policy succeeds or fails. Its experiment should be watched for what it reveals about both the possibilities and dangers of greater resource control.
National ownership does not automatically produce efficient management. A government can own a mine and still mismanage it. It can control petroleum and still import refined products. It can take over gold operations while communities around the mines remain poor. It can remove foreign companies and replace foreign inefficiency with domestic corruption.
Niger itself has already encountered some of these complications. Orano has pursued arbitration over the nationalisation of its interest in SOMAÏR. In September 2025, Reuters reported that about 1,500 tonnes of uranium, valued at roughly $270m, remained stockpiled at the former SOMAÏR mine. Orano had begun arbitration proceedings and warned against the material being transferred or sold without authorisation.
A country seeking greater control over its resources needs competent geologists, engineers, lawyers, accountants, negotiators, regulators and financial institutions. It needs reliable electricity, roads, railways and ports. It needs research institutions capable of developing technology. It needs transparent contracts and systems through which citizens can know what governments receive from their natural resources and how those revenues are spent.
Without these foundations, nationalisation can become an expensive political gesture. But Africa should not allow the imperfections of resource nationalism to become an excuse for maintaining a system in which the continent remains primarily an exporter of raw materials.
Nigeria illustrates the urgency. The country has oil, gas, gold, lithium, iron ore, coal and other minerals, but its economic history has repeatedly demonstrated the danger of exporting natural resources without developing sufficient downstream capacity.
The Tinubu administration has increasingly emphasised local processing and value addition in critical minerals. In July 2026, President Bola Tinubu commissioned a $250m lithium mining and processing plant in Nasarawa State with a capacity of 6,000 tonnes of lithium processing per day. It was described as Africa’s largest lithium processing facility.
Nigeria should not stop at processing lithium. It should be thinking about the battery industry, electric vehicles, energy-storage systems, industrial chemicals, research and the skilled workforce required to support those industries.
The same thinking should apply across Africa. A Congolese citizen living beside cobalt deposits should have access to opportunities created by cobalt. A Zambian living around copper mines should benefit from industries built around copper. A Ghanaian should see gold not merely as something extracted and exported, but as an opportunity for refining, jewellery, financial services and manufacturing. A Nigerien should be able to look at uranium and see engineering, science, technology and industrial opportunities. And a Nigerian should be able to look at oil and gas without accepting that the country’s natural destiny is simply to export crude and import refined products.
If Africa can retain more value from its resources, that value can help finance universities, technical schools, electricity, transport infrastructure, healthcare, manufacturing and technology. Those investments can create productive employment. Productive employment can reduce the economic pressure pushing young Africans towards foreign shores.
The real lesson from Niger, therefore, is not that every African government should wake up tomorrow and nationalise every foreign-owned mine, oilfield or industrial operation. That would be a simplistic reading of what is happening. The lesson is that the old bargain deserves serious reconsideration.
Africa should welcome investors, but it should negotiate better. It should welcome technology, but build its own capacity. It should welcome international capital, but ensure that African capital also grows. It should permit extraction, but demand value addition. It should collect royalties and taxes, but also build industries around the resources generating them.

Riyadh Airport Attacks Threaten Oil, Global Trade

Nigeria’s 2027 Elections and the Unfinished Business of Diaspora Voting, by Boniface Ihiasota

Africa’s Resources Must Build Africa, by Alabidun Shuaib AbdulRahman

Pastor Jerry Eze Defends Miracles At UK Conference Amidst Criticism And Controversy

Diaspora Watch 20th Edition (October 14-20, 2024): Your Trusted Source for Global News and Insights

Tanzanian Man Reportedly Dies And Returns To Life Six Times


-
 News7 days ago
Trump’s Bomber Pullout: Iran Threat Tests US-UK Security Alliance
-
 News7 days ago
Former German spy chief arrested over alleged espionage
-
 Analysis7 days ago
Will Africa Follow Niger Republic? By Alabidun Shuaib AbdulRahman
-
 News7 days ago
Caribbean states seek stronger regional aviation safety oversight
-
 News7 days ago
Tinubu declares three days’ mourning over NAF crash
-
 News7 days ago
10-Year-Old Rainikemba Igbokwe Publishes First Book, Small Boy, Big God